

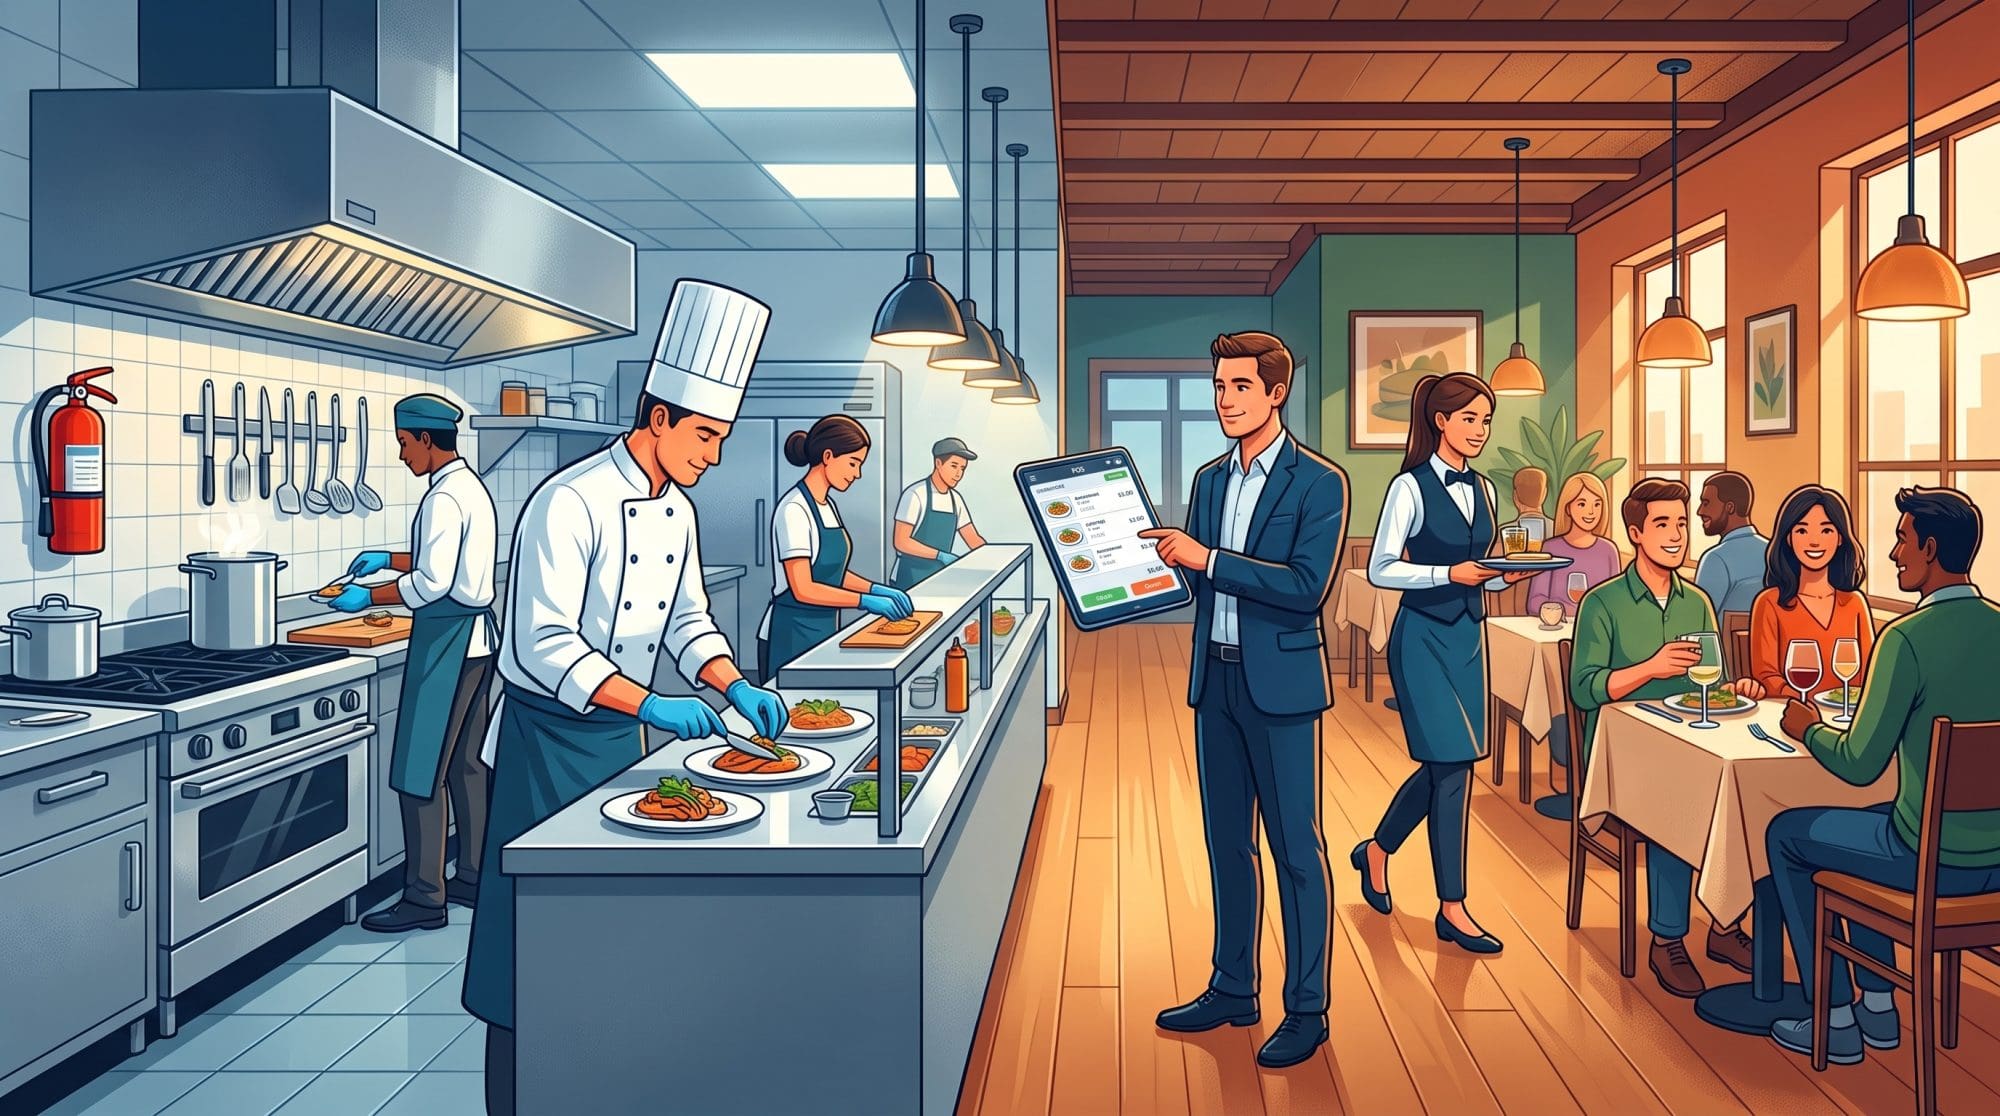
The technical structuring of restaurant insurance requires a combination of property damage and liability coverages. An efficient policy must protect the establishment against commercial kitchen fires, food spoilage, business interruption, and potential food contamination outbreaks, ensuring the financial stability of the operation.
When it is worth it
Purchasing a comprehensive commercial policy is strictly necessary from the very beginning of food service operations. For owners of bars, cafes, and restaurants, this investment mitigates the risk of severe undercapitalization in cases of business interruption and meets the strict contractual requirements demanded by commercial landlords and financial lenders.
Main operational risks
A commercial kitchen environment concentrates critical health and safety exposures. The major risks include fires originating in the exhaust system, bodily injury caused by customer slips and falls on the premises, and food poisoning outbreaks. Furthermore, if the establishment serves alcoholic beverages, liquor liability for incidents involving intoxicated patrons becomes a severe legal exposure.
Common contracting mistakes
A serious technical mistake is configuring the property policy without business interruption coverage, leaving the operator without cash flow to pay suppliers and employees during the months of repair following a structural loss. Another frequent deviation is failing to include specific coverage for stock spoilage in walk-in coolers in the event of a prolonged power outage.
Practical examples
In practice, if a restaurant’s walk-in refrigerator compressor fails overnight, causing the loss of the entire inventory of meat and seafood, a basic physical damage policy will not cover the loss. Without a specific food spoilage clause coupled with equipment breakdown coverage, the operator fully absorbs the replacement cost of the perishable goods.
The architecture of restaurant insurance is based on the structured transfer of property, health, and civil risks. The alignment of liability coverages with the specificities of the operation, combined with protection against loss of income and equipment breakdowns, forms the essential technical foundation to sustain the business with financial resilience and legal robustness.